

Australia’s financial advice sector is undergoing a steady technology shift as advisers adopt digital communication, portfolio management systems and online client services to make financial planning more accessible and responsive.
The sector is now valued at an estimated US$13.51 billion in 2026, with the market projected to almost double to US$26.85 billion by 2031 as digital payments, lending platforms and financial infrastructure continue to reshape the way consumers and businesses manage money.
Around 800 active fintech startups and scaleups are operating across Australia, with locally founded companies accounting for about 96 per cent of the sector.
Digital payments remain the largest segment, representing 20.8 per cent of the market, followed by digital lending and financing at 17.75 per cent.
The transformation is less about replacing advisers with algorithms and more about changing how advice is delivered.
Video consultations, digital documentation, online investment reporting and increasingly sophisticated portfolio-management platforms are allowing financial professionals to work with clients across geographic boundaries while maintaining the personal relationship traditionally associated with financial planning.
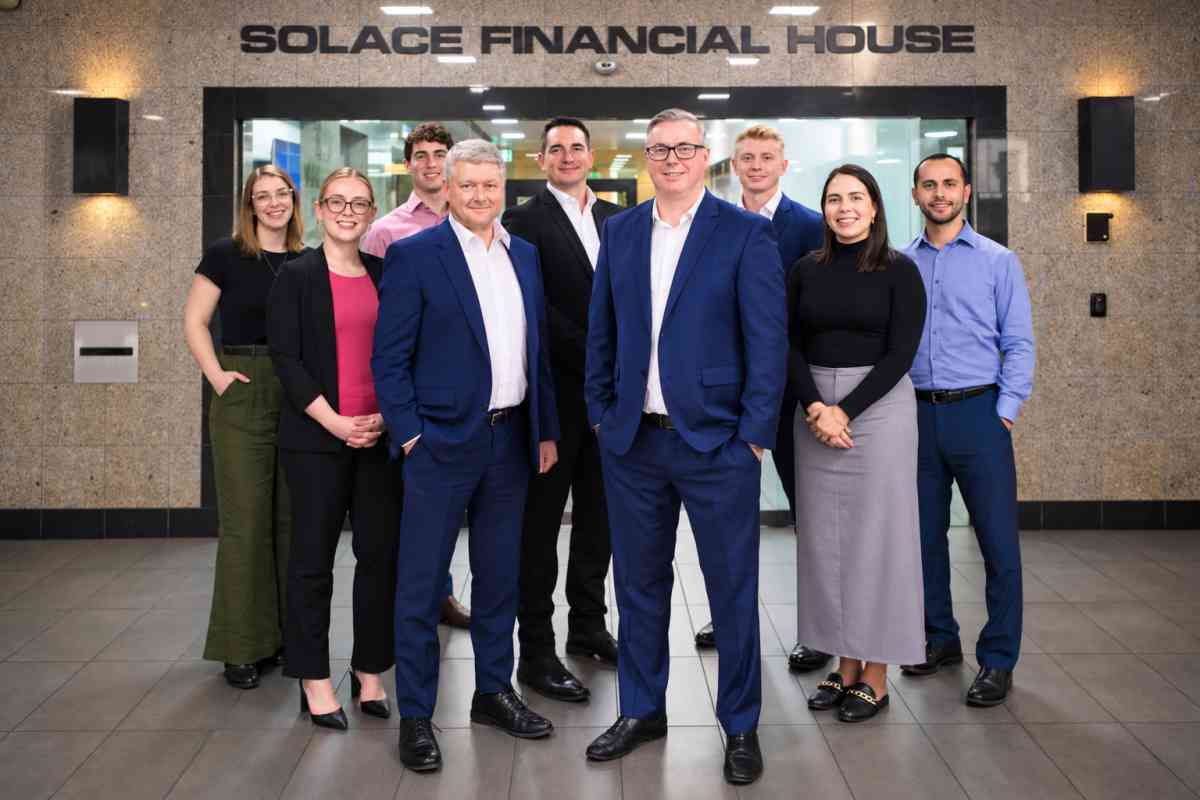
Brisbane-based Solace Financial, and established financial advice practice is currently operating within that changing environment.
The privately owned firm provides investment, retirement, superannuation, wealth management, insurance and generational wealth services, while using technology to support clients beyond its immediate Queensland base.
The company says technologies including Zoom, Microsoft Teams, email and telephone services mean its advisers are no longer limited to face-to-face relationships or clients located within Brisbane.
That relatively simple change reflects a wider development across professional services, where geography is becoming less important to the delivery of specialist advice.
Technology is changing the financial advice relationship
For years, much of the fintech discussion has centred on robo-advice, automated investment applications and low-cost digital investment platforms.
Those services have introduced consumers to a more immediate form of financial management, where balances, investments and market movements can be viewed from a phone within seconds.
Yet complex financial decisions remain difficult to automate completely.
Retirement planning, self-managed superannuation, estate structures, insurance, tax considerations and intergenerational wealth can involve a mixture of financial regulation, personal circumstances and long-term objectives that cannot always be reduced to an automated recommendation.
That is creating an interesting middle ground for the financial services industry. Technology can increasingly handle administration, communication, portfolio visibility and data processing, while advisers concentrate on strategy, interpretation and decision-making.
Solace Financial’s model includes separately managed accounts, which the firm says give its advisers greater control over portfolio adjustments and allow investment allocations to be changed when market conditions move.
The strategies are designed around individual risk profiles and investment objectives rather than being applied as a single standardised portfolio.
This type of portfolio infrastructure highlights an important part of financial technology that receives less attention than consumer-facing fintech apps.
Some of the biggest changes are occurring behind the scenes, where advisers are gaining better systems for managing investments, communicating with clients and monitoring financial strategies.
Digital access is breaking down geographic barriers
Remote financial advice has also changed the addressable market for smaller and independently owned advisory firms.
A financial planning business that once depended heavily on clients living within travelling distance of an office can now maintain relationships interstate through digital meetings and electronic communication.
That does not eliminate the value of face-to-face advice, particularly when clients are dealing with retirement, major financial events or complicated family circumstances. It does, however, give consumers considerably more choice when deciding who should manage or advise on their finances.
Solace Financial operates from Brisbane and serves clients across Queensland, but says it also works with clients interstate using online communication technologies.
The firm’s advisers collectively have more than 80 years of professional experience, while its history extends back to 2013 and the former Whittaker Macnaught group. Solace Financial operates through an Australian Financial Services Licence structure, with SFDS Pty Ltd holding AFSL 509493.
That regulatory distinction remains important as financial services become increasingly digital.
A polished website or investment platform can make almost any financial service appear sophisticated, but technology does not remove the licensing, disclosure and professional obligations attached to personal financial advice.
Fintech is moving beyond the app
The next stage of financial technology may therefore be considerably less visible than the first.
Consumers are already accustomed to mobile banking, instant payments, digital brokerage services and app-based investing. The greater change now taking place is the integration of technology into conventional professional services.
Financial advisers can increasingly communicate remotely, monitor portfolios electronically and provide clients with faster access to financial information while retaining a human adviser responsible for the broader strategy.
This hybrid model could prove particularly important as Australia’s population ages and financial circumstances become more complicated.
Retirement planning increasingly intersects with superannuation, investments, property, taxation, aged care and estate planning, creating financial decisions that can stretch well beyond the capabilities of a basic investment application.
Technology can organise information and remove administrative friction, but the financial advice industry is discovering that digital transformation does not necessarily mean removing people from the process.
Instead, the more significant shift may be giving advisers better technology while giving clients faster access to those advisers, regardless of where either happens to be located.
With the Australian fintech market forecast to grow at an annual rate of 14.72 per cent through to 2031, financial services firms that combine technology with established advisory expertise are likely to become an increasingly important part of the sector.